

Seven in 10 Kenyans Unprepared for Comfortable Retirement, Study Finds
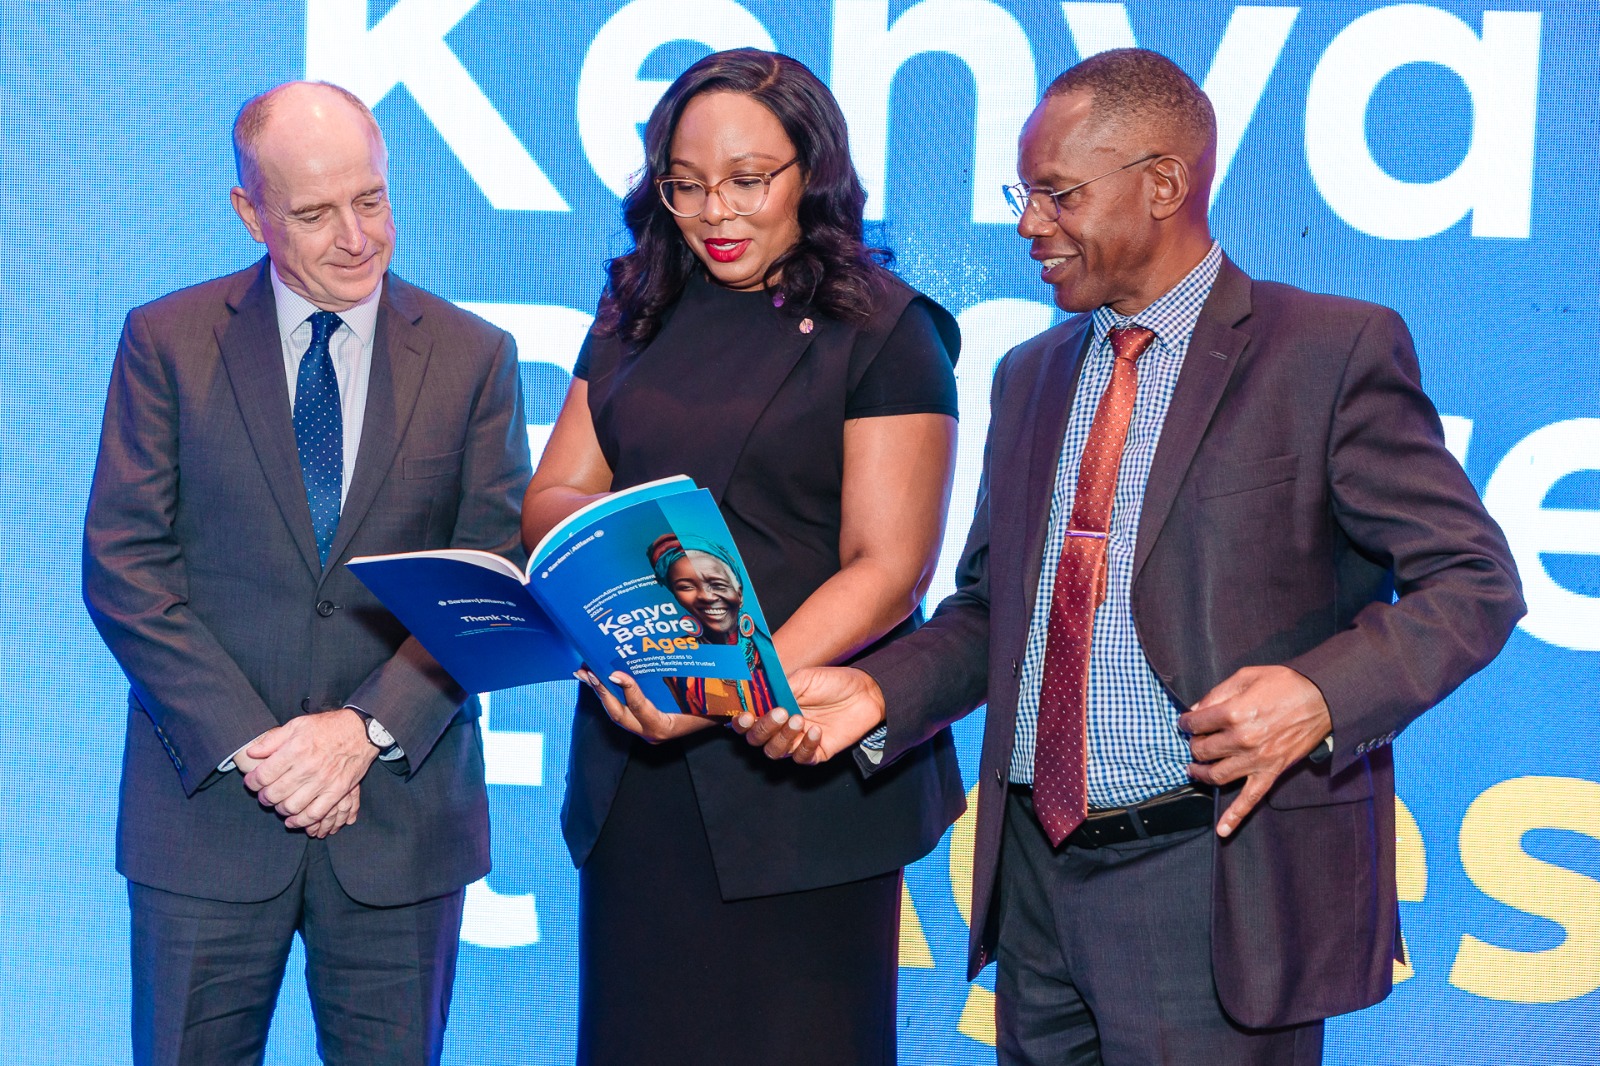
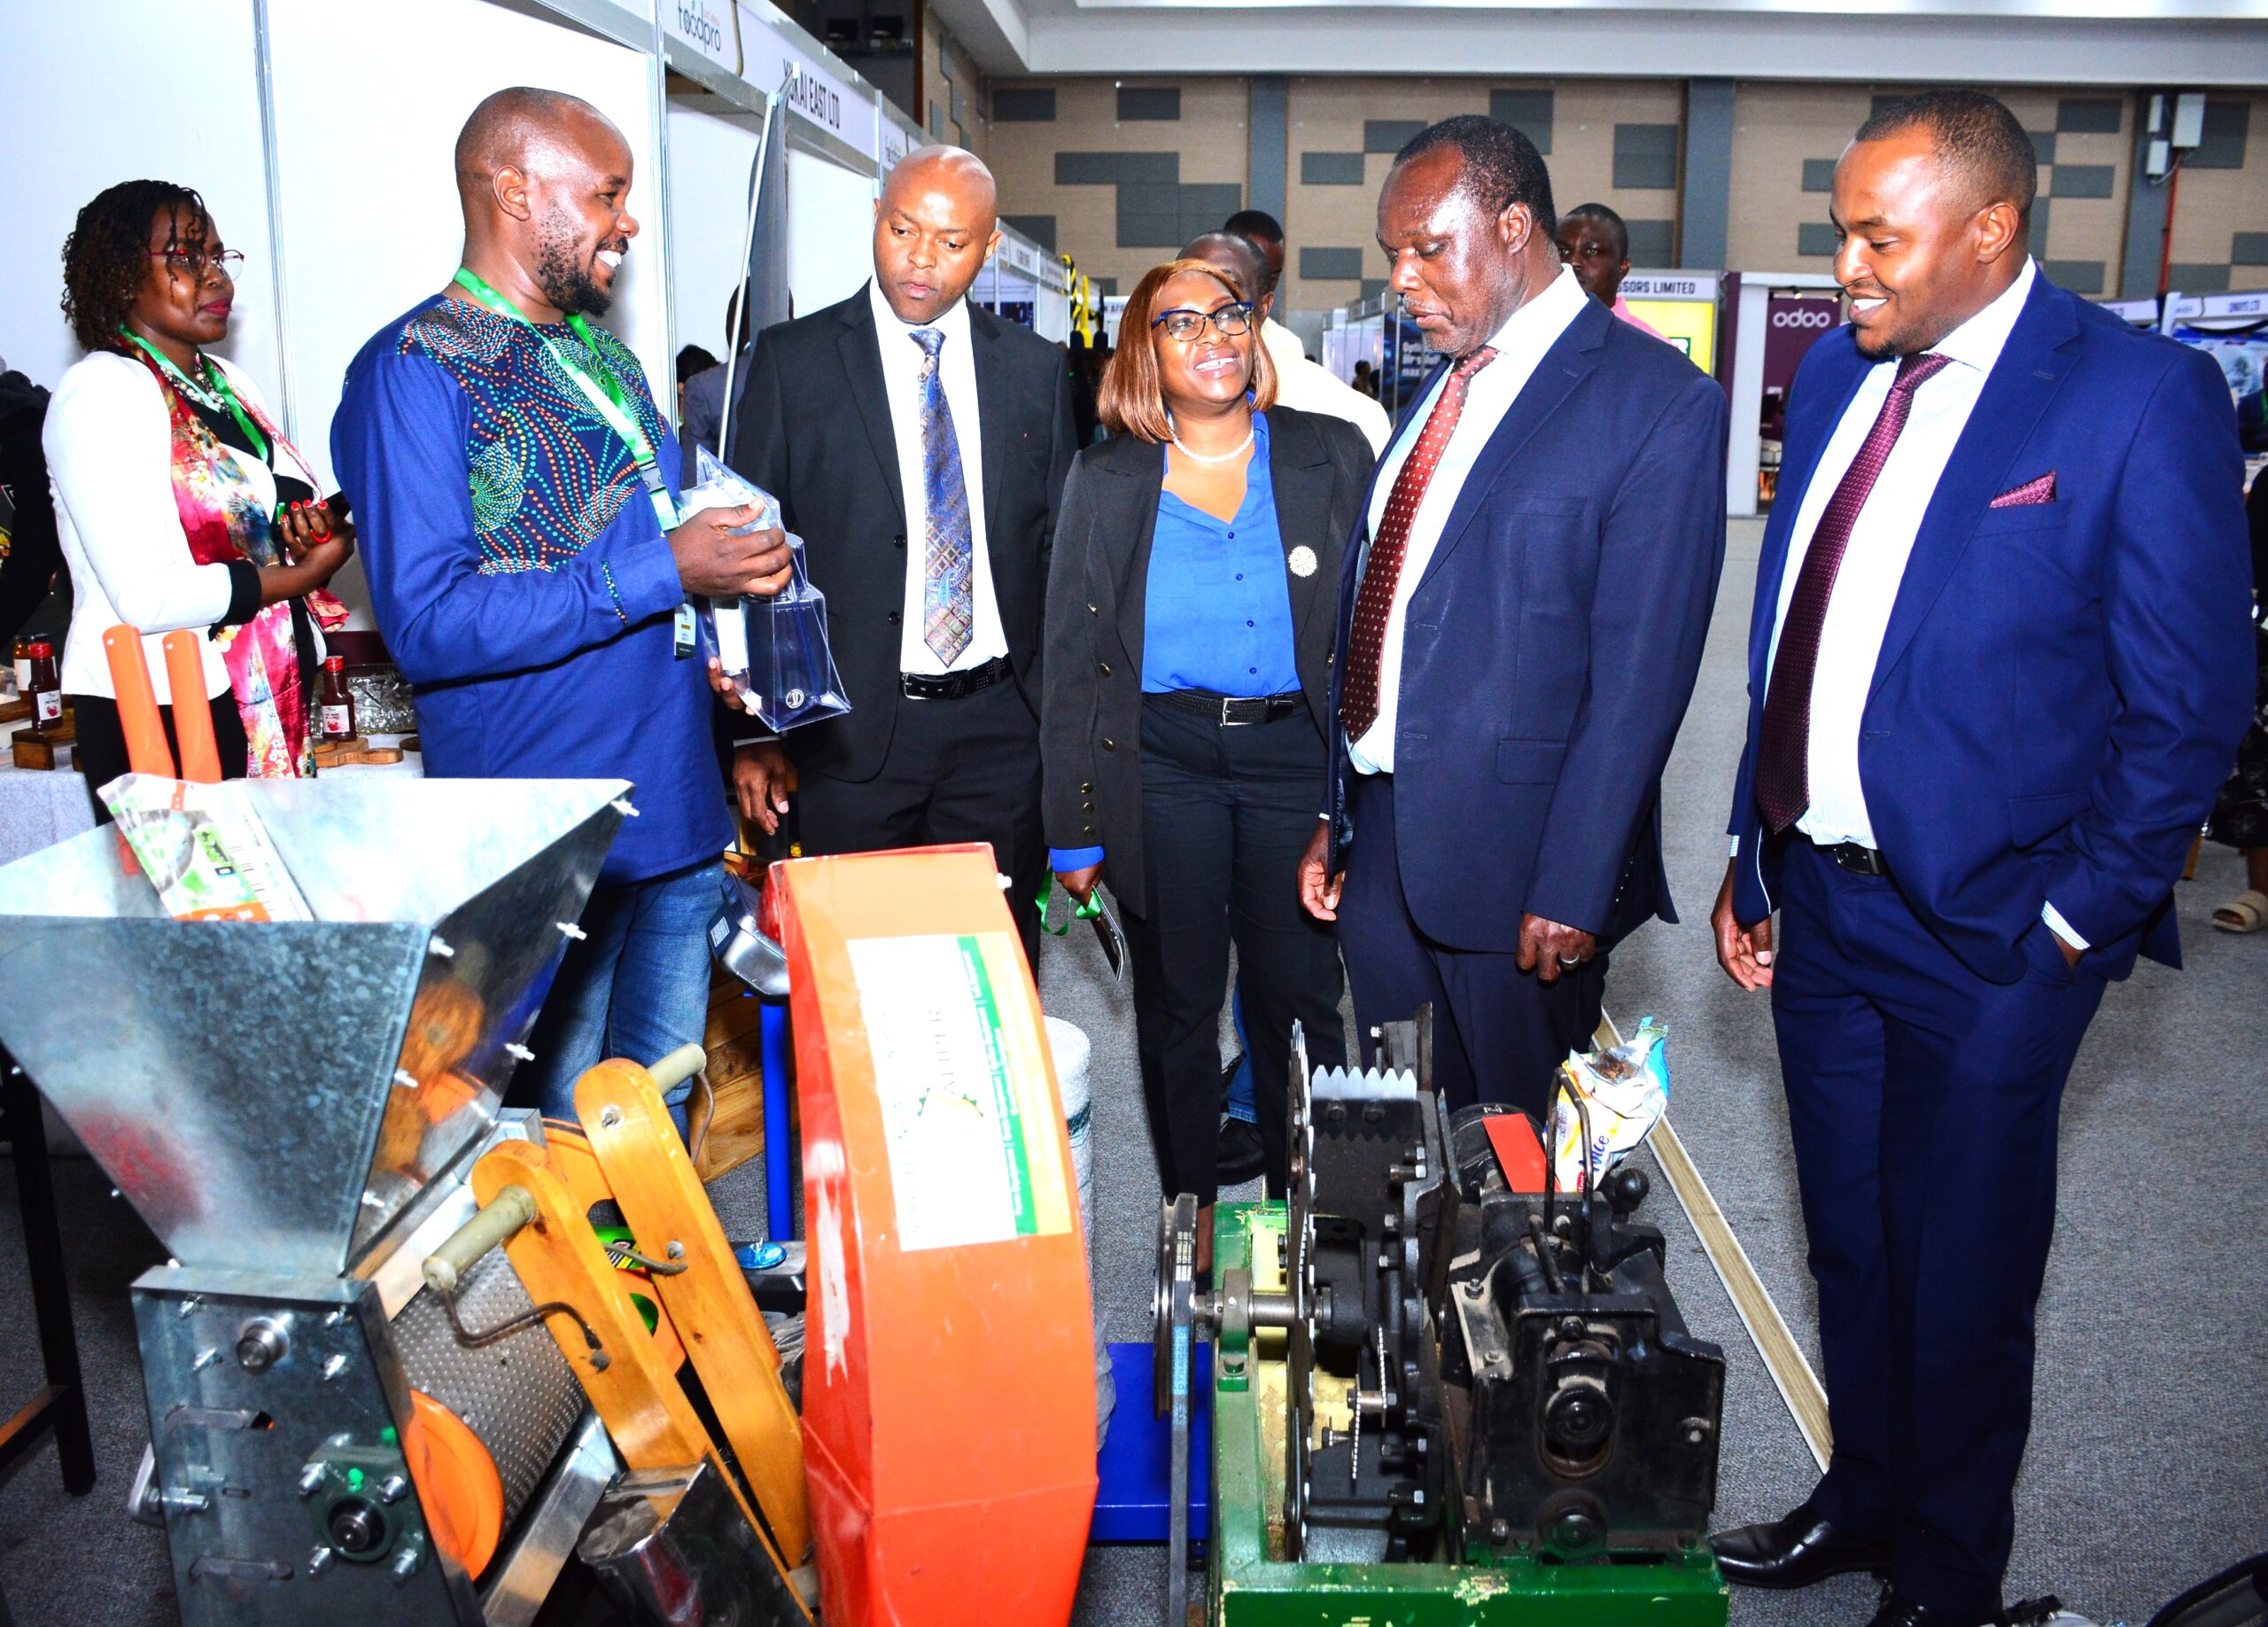
Jacqueline Karasha (centre), Jonathan Stichbury (left) and Dr Nyamemba Patrick Tumbo (right) examine the SanlamAllianz Kenya Retirement Benchmark Report 2026 during its launch in Nairobi on October 12, 2026.
Seven in 10 Kenyans are not on track for a comfortable retirement, with household expenses, irregular incomes and debt repayments limiting their ability to save, a new study has revealed.
The inaugural SanlamAllianz Kenya Retirement Benchmark 2026 shows that despite widespread awareness of the importance of retirement savings, many Kenyans struggle to preserve their savings and plan for a reliable income in old age.
The study, released in Nairobi on Monday, found that family and household expenses were the biggest barrier to retirement saving, cited by 44 per cent of respondents, followed by low or irregular income at 37 per cent and debt repayments at 24 per cent.
Only four per cent attributed their failure to save to a lack of understanding or trust in retirement products, suggesting that financial pressures, rather than awareness, remain the main obstacle.
Sanlam Allianz Life Insurance (Kenya) Limited Chief Executive Officer and Principal Officer Jacqueline Karasha said the country had made significant progress in expanding financial access and inclusion, but needed to translate that progress into long-term financial security.
“Retirement should be a stage of life that offers dignity, independence and choice, not one where people are forced to scale back their ambitions,” she said.
The report found that 62 per cent of respondents said supporting dependants reduced the amount they could save, while 39 per cent could meet basic household expenses for only two months or less if their income stopped.
In the past year, 23 per cent of respondents had dipped into their savings or reduced retirement contributions when finances became strained, with the proportion rising to 29 per cent among earners aged 20 to 39.
Retirement savings withdrawals raise concern
The study also highlighted challenges in preserving retirement savings when people leave employment or businesses.
Among respondents who left a job or business while holding retirement savings, 53 per cent withdrew at least part of the funds, while 26 per cent cashed out the entire amount.
Only 32 per cent retained or transferred their full savings, while a third used the money to start or support a business or farm.
Although 65 per cent said they understood the implications of withdrawing their savings at the time, 53 per cent later regretted the decision. One in five respondents said they received no assistance when leaving their employment or business.
Karasha said retirement planning required more than creating awareness, calling for practical measures to help workers preserve their savings during periods of transition.
“This is why preservation cannot rely on awareness alone,” she said, adding that the industry had a responsibility to provide relevant guidance and develop solutions that reflect people’s financial circumstances.
Limited retirement income planning
The findings further revealed gaps in retirement planning, with one in five working-age contributors unaware of how much they had saved.
Only 29 per cent knew the monthly income they would require during retirement, while 45 per cent had never heard of income drawdown, a mechanism through which retirement savings can provide periodic payments.
Despite the limited awareness, 51 per cent said they wanted a guaranteed monthly income for life.
The report also found that 53 per cent had no funded plan to meet medical expenses after retirement, potentially exposing them to financial pressure as they aged.
Meanwhile, 88 per cent of respondents said they would continue working or running a business even if their retirement income was sufficient to meet their needs.
SanlamAllianz Investments Limited Managing Director and Chief Executive Officer Jonathan Stichbury said retirement security should be measured by the income savings could sustain rather than the accumulated balance alone.
“Retirement security is ultimately not about the balance someone accumulates during their working years, but whether those savings can provide a reliable income throughout retirement,” he said.
Informal employment and digital risks
The study comes against the backdrop of an economy in which informal employment accounts for a substantial share of new jobs.
According to the Kenya National Bureau of Statistics (KNBS) 2026 Economic Survey, Kenya’s economy grew by 4.6 per cent in 2025, while the informal sector accounted for 87.2 per cent of new jobs.
Among working respondents in the benchmark, 39 per cent said their earnings fluctuated from month to month, while 51 per cent of informal workers preferred making retirement contributions through mobile money.
However, digital financial services also presented risks, with 45 per cent of respondents reporting that they had lost money or personal information through digital financial scams. The proportion rose to 54 per cent among younger respondents.
A trusted provider or regulator emerged as the leading feature respondents wanted when choosing a retirement product.
SanlamAllianz Kenya Group Chief Executive Officer Dr Nyamemba Patrick Tumbo said Kenya had an opportunity to strengthen retirement preparedness while the population remained relatively young.
“Through the SanlamAllianz Kenya Retirement Benchmark, we aim to measure progress, stimulate dialogue and support the decisions needed to improve retirement outcomes for future generations,” he said.
The company said it would repeat the benchmark annually to monitor changes in retirement preparedness and savings behaviour.
The inaugural study was based on an online survey of 300 Kenyans, including income earners aged 20 to 39, those aged 40 to 64 and retirees.
The report cautioned that its findings were indicative rather than nationally representative, given the sample size and survey methodology.